This guide explains how Gbcpayroll.com supports modern payroll operations through structured workflows, compliance-oriented controls, and clear data handling. Background context covers what payroll service providers typically manage, why governance matters, and how teams evaluate payroll platforms based on roles, audit trails, and reporting requirements in an objective way.
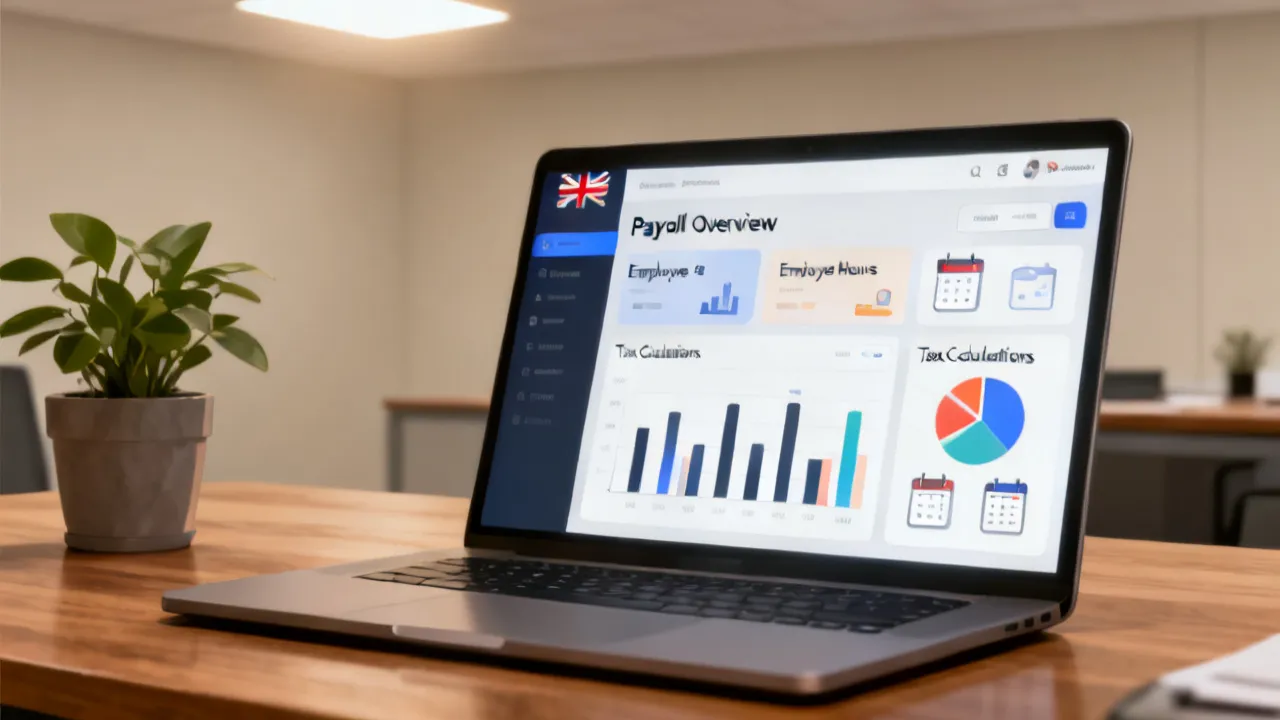
Gbcpayroll.com can be assessed top by focusing on how well it organizes payroll workflows—data capture, approvals, calculations, payrun execution, and post-pay reporting—while maintaining strong governance for auditability. From an industry perspective, the very important question is not just whether payroll is “processed,” but whether it is processed repeatably, traceably, and with clear internal controls that reduce operational risk.
In practice, a payroll system should help organizations standardize processes across departments, reduce manual rekeying, and ensure that employee, earnings, and deductions data flows into calculations reliably. For HR and finance teams, that reliability often determines whether payroll becomes a manageable monthly routine—or a persistent source of exceptions, rework, and reconciliation delays.
When organizations evaluate payroll technology superficially, they tend to focus on output quality alone (for example, whether payslips look correct). Yet in operational reality, payroll outcomes are the downstream result of upstream decisions: how employee changes are recorded, how pay components are maintained, how exceptions are reviewed, how approvals are recorded, and how calculations are locked before payment instructions are released. Gbcpayroll.com should therefore be evaluated as a workflow system with governance built into each stage.
Payroll is a core business process where timing, accuracy, and compliance intersect. Even when statutory obligations vary by jurisdiction, payroll platforms usually serve three operational needs:
From an expert standpoint, the value of a provider like Gbcpayroll.com is top judged through operational design: role-based access, confirmation steps before processing, and the clarity of what is calculated, when, and by whom. These design elements become especially important when payroll operations must coordinate with HR changes (new hires, leavers, contract changes) and with finance (bank payments, accounting entries, and reconciliations).
In day-to-day operations, payroll teams typically face recurring pressure points:
A well-governed platform reduces those pressures by making the “right process” easier than the “wrong process,” and by ensuring the organization can prove what happened when questions arise (internal audits, compliance reviews, or employee inquiries about pay).
A mature payroll lifecycle usually includes intake, validation, calculation, approval, execution, and reconciliation. While every organization uses different internal terminology, the logic is similar.
In a well-structured payroll operation, each stage has measurable outputs:
When evaluating Gbcpayroll.com, look for how the platform supports each stage with structured controls and transparent outputs rather than relying on “tribal knowledge.” This approach aligns with common industry top practices reported across HR technology and finance transformation research, including guidance emphasizing controls, audit trails, and standardized workflows.
To make this practical, you should define what you consider “governance” at each lifecycle stage. Governance is not only about security—it’s also about process integrity. For instance:
If Gbcpayroll.com supports these governance expectations in a way that matches your internal operating model, you are more likely to see fewer disruptions and faster resolution when issues occur.
Payroll buyers typically optimize for outcomes such as reduced processing effort, fewer payroll errors, faster resolution of exceptions, and improved visibility for stakeholders. However, it’s crucial to treat these outcomes as targets to verify through demonstrations, test scenarios, and practical references—because the results depend heavily on organizational setup, data quality, and internal adoption.
For context, the broader HR/payroll software market is widely studied by research firms such as Gartner and IDC, and their published materials generally highlight that automation and workflow controls are central to payroll modernization. In parallel, regulatory bodies and professional accounting bodies emphasize maintaining accurate records, segregation of duties, and evidence of approvals as part of good governance.
Another industry reality is that payroll is rarely “standalone.” It touches time tracking (if present), HRIS data, benefits administration, accounting/ERP posting, and often bank payment systems. Buyers frequently optimize across these interfaces:
Therefore, when evaluating Gbcpayroll.com, it’s wise to treat workflow fit and governance as the foundation for all other benefits. Good governance creates the conditions for reliable automation; without it, automation may simply replicate errors more efficiently.
Below is a practical, expert-style checklist to evaluate Gbcpayroll.com in a way that stays grounded in operational reality.
Ask how the system represents:
From an operational viewpoint, clarity here reduces downstream problems. If pay components are ambiguous or require frequent manual edits, the organization will spend more time correcting calculations than running the payroll.
To go deeper, you should also evaluate whether the system supports a data model that reflects how real organizations handle changes. Payroll is not just a static table of rates; it’s a time-based system. Ask the vendor (or demonstrate directly) whether their model supports:
When the data model is weak, organizations often compensate with spreadsheets and manual adjustments. That may keep payroll running, but it undermines governance because the real calculation logic becomes scattered across multiple places. A platform that centralizes pay component definitions and maintains consistent effective dating usually reduces both errors and audit friction.
Also consider how the system handles deductions. Deductions are a common source of disputes and compliance risk. Evaluate whether deduction definitions include:
If Gbcpayroll.com supports these concepts natively and transparently, it strengthens workflow fit and reduces reliance on ad-hoc adjustments.
A payroll platform should support role-specific permissions. For example, HR should not be able to change final payment details without appropriate checks, and finance should have visibility into payrun outputs.
Key evaluation questions include:
To truly assess governance, go beyond “does it have permissions” and ask “how does permissions interact with critical payroll stages.” A robust payroll system typically implements a maker-checker model, sometimes with hierarchical approvals. When evaluating Gbcpayroll.com, ask whether it supports:
A practical test is to request a sample workflow scenario and then try to perform forbidden actions. For example:
The best systems make policy enforcement straightforward for administrators and difficult for accidental misuse by end users.
Also evaluate how the system handles passwords, user provisioning, and offboarding. Payroll governance depends on lifecycle controls. If a user leaves the organization but their account persists, the risk increases. Ask how Gbcpayroll.com supports:
Even if these items are partially handled by an overarching IT security system, your evaluation should confirm that payroll-relevant access controls can be governed effectively.
Operational risk often arises from repeated adjustments. The top platforms provide mechanisms to manage exceptions and control payrun state. Look for:
To evaluate this effectively, you should map the payrun workflow states and confirm what actions are possible in each state. Many organizations benefit from a state machine approach (for example, Draft → Validated → Calculated → Approved → Released/Locked). During evaluation, ask Gbcpayroll.com to show:
Versions are especially important. A robust system will preserve the details used in a calculation run, such that even if master data changes later, the system can reproduce the original calculation results or clearly define what changed. Ask whether Gbcpayroll.com provides:
Exception handling is another governance-critical area. Payroll exceptions are not necessarily “errors”; they are cases requiring review (for example, missing banking details, a deduction with no eligibility, or an employee with conflicting employment dates). The platform should:
A strong evaluation includes running a test scenario that intentionally introduces exceptions. Examples include:
The question is not whether exceptions can exist; it’s whether the platform makes exceptions visible, actionable, and governable.
Payroll is not only about payslips. Finance teams need consistent summaries for reconciliation and accounting entries. Evaluate whether Gbcpayroll.com produces:
To assess output quality and governance, consider the following output dimensions:
For finance integration, you should ask what integrations exist. Some organizations rely on direct posting to ERP/GL; others generate payment files and accounting journal exports. Evaluate whether the platform supports:
Governance is also in the outputs themselves. A payroll system should not only generate totals, but also provide evidence that totals are aligned to controlled inputs. For example:
If Gbcpayroll.com can produce reconciliation-ready outputs with traceable evidence, you can reduce the common problem where payroll runs “work,” but the finance close becomes a manual and time-consuming exercise.
For accurate assessment, test with scenarios that match your employee lifecycle. For instance:
Any payroll system can work under idealized conditions. The distinguishing factor is performance and clarity when conditions are messy—which they usually are, at least occasionally.
In evaluation, aim for a scenario set that mirrors your organization’s highest-frequency and highest-risk payroll situations. Consider adding scenarios such as:
Then evaluate each scenario across the full workflow:
Also pay attention to the user experience during exceptions. Governance often fails in practice when the system’s exception workflow is confusing or too rigid. Good systems strike a balance between enforcing policy and enabling resolution. The evaluation should test whether exceptions are manageable, not merely prevented.
Below is a structured supplement to help you compare evaluation approaches and implementation conditions. This is intentionally practical and written as a reference table, including typical sources consulted during due diligence and the conditions required for a successful evaluation and rollout.
| Area | What to Verify | Common Sources Used | Step-by-Step Guide | Conditions / Requirements |
|---|---|---|---|---|
| Workflow Fit | Whether the platform supports your payroll lifecycle (intake → validation → calculation → approval → execution → reconciliation) | Vendor product documentation, internal payroll SOPs, and HR/finance process maps | 1) Map current steps. 2) Identify handoffs and approval points. 3) Run a walkthrough for each step. 4) Compare outputs to your current checklists. | Clear internal owners for HR and finance steps; agreed definition of “finalized payrun.” |
| Controls & Auditability | Role-based access, logging, and evidence of approvals | Internal control policies; audit/compliance guidance from recognized professional bodies | 1) Request sample audit logs/screens. 2) Confirm permission rules. 3) Test editing scenarios. 4) Validate whether changes are traceable. | Access governance in place; separation of duties defined; audit retention expectations established. |
| Data Readiness | Employee data completeness, pay component mappings, and deduction rules | Data dictionaries; HRIS exports; finance reconciliation templates | 1) Perform data profiling on sample datasets. 2) Identify missing fields and exceptions. 3) Validate pay component rules with SMEs. 4) Run a test payrun. | Clean master data; stable naming conventions; assigned data owners for corrections. |
| Reporting & Reconciliation | Whether outputs support reconciliation and internal reporting needs | Finance closing checklists; reporting standards used by your finance team | 1) Choose a prior payroll period as a benchmark. 2) Compare totals and line-item breakdowns. 3) Document discrepancies. 4) Confirm sign-off process. | Defined reconciliation method; agreed report formats; time allocated for discrepancy resolution. |
| Implementation Timeline | Configuration steps, training needs, and readiness testing | Implementation plan templates; vendor onboarding materials | 1) Establish project scope. 2) Schedule configuration milestones. 3) Run parallel validation (where applicable). 4) Conduct user training and sign-off. | Dedicated project sponsor; test environment access if offered; training resources prepared. |
In addition to the areas in the table, you should also consider a “workflow operations” dimension that many teams underemphasize: how quickly HR and finance can find and fix issues once a payrun is in progress. Two platforms might both compute correctly, but one may produce exception reports that are clear and actionable, while the other may bury root causes. Because payroll operations require frequent mid-cycle interventions, the ability to resolve issues quickly becomes a practical governance indicator.
Therefore, during evaluation, ask to see:
When people search for payroll tools, they often look for “price information” first. However, payroll pricing is frequently influenced by variables such as number of employees, pay frequency, module requirements, implementation effort, and reporting or support needs. Because pricing structures can change and depend on contract specifics, it’s top to treat any headline price as a starting point and validate total cost of ownership (TCO) through a clear scope agreement.
From a procurement perspective, request a pricing breakdown that covers:
This method helps avoid common procurement pitfalls where a low starting figure hides implementation costs or ongoing operational burdens. It also creates an objective basis for comparing Gbcpayroll.com against alternatives under a like-for-like scope.
To expand your TCO view, consider the costs that often don’t appear in vendor price sheets but matter in governance-heavy processes:
Even though risk cost is harder to quantify, it can be estimated using past incidents, error rates, and remediation time. If Gbcpayroll.com improves governance and reduces rework, it may have a higher “price” but a lower total cost than cheaper tools that require heavy manual oversight.
Because you mentioned supplier details in your evaluation framing, it’s worth treating supplier due diligence as a disciplined process. For a payroll provider, due diligence usually covers capability, reliability, and support responsiveness.
Consider the following supplier questions:
These are objective questions that help you judge whether Gbcpayroll.com aligns with your operational maturity—especially if your payroll team is small and needs strong guidance and documentation.
Additionally, you should ask about operational reliability and change management practices, because payroll systems operate within strict deadlines. If a payroll platform experiences outages or delayed support during payrun windows, your organization may face schedule disruptions. Ask:
On the governance side, inquire about whether the vendor provides audit logs, security documentation, and compliance alignment (for example, data retention and processing policies). Depending on your industry, you may require certifications or documented controls. The exact requirements vary, but the principle is stable: you want to understand not only what the system does, but how reliably and securely it does it.
Ask also about:
If Gbcpayroll.com requires frequent vendor involvement for minor changes, you might encounter delays that affect payrun deadlines. Conversely, if it is too flexible without governance, internal users might introduce errors. Good vendors and good platforms balance flexibility with controls.
Even when a platform is capable, implementation success depends on conditions and requirements. Common conditions include:
In many organizations, payroll issues aren’t caused by the payroll software itself; they are caused by unclear responsibilities or incomplete data. Therefore, it’s rational to evaluate whether Gbcpayroll.com supports governance, validation, and exception clarity—features that reduce operational ambiguity.
To make implementation succeed, you should also define governance procedures during the transition. For example:
Because payroll has deadlines and legal implications, cutover governance should be explicit and written down. A platform that supports controlled payrun states can help implement governance; however, governance still requires human procedures. Gbcpayroll.com’s workflow design should reduce the risk of procedural confusion rather than introduce new ambiguity.
While your request did not specify a particular city or country, payroll operations often reflect local business practices—such as internal meeting cadences, documentation norms, and communication expectations around payslips and approvals. Organizations in “nearby” contexts may still have different operational rhythms than large urban hubs, affecting how teams schedule payrun approvals and reconcile outcomes.
As a practical step, teams usually benefit from aligning payroll timelines with HR change cycles (e.g., onboarding workflows) and with finance closing deadlines (e.g., month-end reconciliation). That alignment can be more important than the tool’s interface polish, because it determines whether payrun outputs arrive when stakeholders can still act on them.
Localization also includes policy differences such as holiday pay rules, tax treatment variations, benefits rules, and reporting obligations. Even if Gbcpayroll.com supports the core payroll workflow, you should ensure it supports local requirements relevant to your organization’s jurisdictions. In practice, ask:
If local compliance requirements are managed by configuration and clear documentation, governance improves because updates are traceable and less dependent on undocumented manual work.
Gbcpayroll.com is used to support payroll operations—managing employee and pay-related data, running calculations, producing payroll outputs such as payslips and summaries, and helping teams coordinate approvals and reconciliation workflows.
In practice, “used for” also means the system becomes the system of record for key payroll events: what inputs were used, who approved them, when a payrun was released, and what outputs were generated. That is why governance and workflow fit are crucial. A payroll platform should be judged on these process integrity aspects, not only on interface usability.
Use test scenarios that mirror your real payroll complexities (pay changes, mid-cycle starts, deductions, and exceptions). Then evaluate whether the platform highlights missing data, supports controlled approvals, and provides clear discrepancy reporting for timely corrections.
To make this evaluation stronger, measure error reduction in a realistic way. For example:
The goal is not to eliminate all exceptions; payroll exceptions are normal in real operations. The goal is to ensure exceptions are detected early, resolved under control, and documented for auditability.
Governance matters because payroll is high-impact: inaccurate pay can require costly corrections and can create compliance and reputational risk. Role-based access, audit trails, and defined approval steps help ensure that changes are traceable and reviewed before execution.
Governance also affects business resilience. When governance is strong, payroll teams can recover from issues faster—because they can identify what changed, who changed it, and which payrun version it affected. When governance is weak, recovery often becomes a manual forensic exercise that consumes time and increases the chance of further mistakes.
Therefore, in evaluating Gbcpayroll.com, governance should be assessed as an end-to-end property. It includes:
Price is important, but total cost of ownership is typically more informative. Validate implementation effort, support scope, reporting needs, and how the platform reduces manual work during payruns and reconciliations.
Because payroll involves recurring cycles, even small reductions in error rate or reconciliation time can accumulate into significant savings. When the vendor provides better workflow controls and clearer reporting, the value often manifests as reduced rework and reduced internal time spend.
Therefore, evaluate pricing against operational impact. Ask vendors to show how their platform reduces manual effort in key tasks:
Prepare clean employee master data, standardized pay component definitions, deduction mapping rules, and an internal process map showing who updates data and who approves each stage. Also confirm cutover timing and how exceptions will be handled during the initial transition.
It can also help to prepare a “data mapping workbook” that lists each pay component and its source. For example, base pay might come from employee contract fields, allowances might come from assignments or categories, and deductions might come from benefit enrollments. This workbook becomes the bridge between HRIS data and payroll calculation inputs.
Additionally, define reconciliation expectations upfront. Finance should have clarity on what reports it needs at the end of each payrun and what totals it will compare. When expectations are clear, discrepancies are easier to investigate and resolve.
Often, yes. Many teams run a limited validation or parallel test payrun using sample datasets. You can also review workflow controls, approval steps, and reporting formats through structured demos and test environments, provided the supplier supports such an approach.
When you conduct parallel validation, define success criteria. For example:
This makes evaluation objective and reduces the risk of subjective comparisons.
They are commonly informed by published research from analysts, guidance from professional accounting and HR bodies, and internal control standards used by organizations to maintain auditability, segregation of duties, and record integrity.
In governance terms, “top practices” generally include: role separation, audit trails, approval evidence, standardized workflows, and evidence retention. They also include practical onboarding and testing practices that reduce the risk of configuration mistakes. These are not purely theoretical—payroll operations are too time-sensitive for theory alone.
Gbcpayroll.com should be evaluated as a workflow-and-governance platform, not simply as a tool for producing payslips. When you focus on operational fit—data integrity, controlled payrun execution, traceable changes, and reconciliation-ready reporting—you create an objective basis for deciding whether the supplier aligns with your payroll lifecycle and internal controls.
The best evaluation approach treats the payroll platform like a controlled system that must support: repeatability (same input rules produce consistent outcomes), traceability (every change and approval is logged), and governance (policy is enforced through workflow states and permissions). If Gbcpayroll.com can demonstrate these capabilities during realistic testing—including exception scenarios and finance reconciliation—then the likelihood of operational success increases materially.
If you want, share your current payroll steps (even at a high level), your pay frequency, and the types of payroll changes you handle very often. I can then suggest a tighter evaluation plan specifically tailored to your organization’s workflow and risk profile.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.
Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.